

CPOS: Tap to Pay Card Reader
CPOS
- 4.4
- 155.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
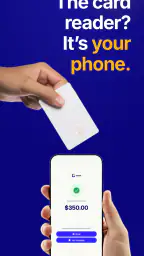
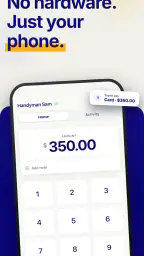
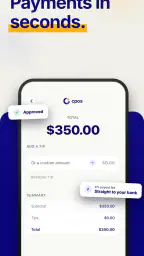
CPOS: Tap to Pay Card Reader Pros and Cons
Pros
- Accepts contactless payments directly from a compatible smartphone.
- Reduces the need for dedicated card-reading hardware.
- Useful for mobile sellers, freelancers, and small businesses.
- Can help speed up checkout in busy customer-facing situations.
- Portable setup works well for pop-up shops and off-site sales.
Cons
- Requires an NFC-enabled device and compatible operating system.
- Availability and features may vary by country or payment provider.
- Transaction fees can reduce earnings on frequent small payments.
- A reliable internet connection may be needed to process transactions.
- Battery drain can be noticeable during extended payment sessions.
 Analysis by All-app
Taking a card payment can become surprisingly awkward when the customer is ready, the queue is growing, and the only reader is in another bag, behind another counter, or out of battery. CPOS: Tap to Pay Card Reader approaches that problem from a simple angle: use a compatible phone as the point where a customer taps to pay, rather than carrying a separate card terminal. In my experience, that makes the app most interesting for small businesses, mobile sellers, and anyone who occasionally needs to accept payment away from a fixed checkout.
CPOS is a free business app from CPOS, with an Everyone age rating. It has reached over ten thousand installs and holds a 4.4 average from more than two hundred ratings, which suggests that the idea is connecting with a useful group of users rather than being a purely experimental tool. The app was released in January 2025, and version 2.34.0 is the version I reviewed.
The important thing is not simply that a phone can read a tap. The real benefit is the time and equipment saved when a normal card reader would be excessive. A market stall, a tradesperson finishing a small job, or a café handling an outdoor queue may not want another device, another charger, and another item to remember. CPOS is built around that lighter workflow. It does not try to turn a phone into a complete retail system by magic; it focuses on the payment moment and makes that moment easier to carry around.
Where CPOS earns its place in a busy working day
I look at CPOS through the everyday decisions that make a mobile payment feel dependable: getting the phone ready, confirming the amount clearly, and having a fallback when the usual setup is unavailable. This section focuses on where that phone-first approach can fit into a working day, while keeping the choice of payment setup in the seller’s hands.
The recurring payment problem is usually small, but costly
Many payment frustrations are not dramatic failures. They are little delays: looking for the terminal, waiting for it to wake, realizing it has no charge, moving a customer from one counter to another, or asking someone to pay later because the business is temporarily away from its usual setup. Those interruptions are especially noticeable when the transaction itself should take only a few seconds.
That is where a phone-based reader makes sense. I can keep the payment point with me instead of treating it as a fixed object. For a mobile service, this changes the order of work. I can finish the job, confirm the amount, and handle payment while I am still with the customer. For a small event, I can move between locations without carrying a dedicated terminal. The advantage is less about novelty and more about removing a handoff.
There is also a practical psychological benefit. Customers generally understand the gesture of tapping a card or compatible device, so the interaction does not require a long explanation. The phone becomes the visible payment surface, while the seller avoids presenting a complicated collection of hardware. That can make a one-person operation feel more organized without forcing it to imitate a large store.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Still, I would not judge the app only by whether it can accept a tap. A payment tool has to fit the way a business works. If the business needs printed receipts, inventory control, staff permissions, detailed product management, or a countertop terminal designed for constant use, a dedicated point-of-sale system may remain the better choice. CPOS is strongest when the main problem is accepting a payment conveniently, not managing every part of a shop.
My first useful setup was about preparation, not complexity
The first thing I would do with CPOS is prepare it before the customer is standing in front of me. A phone-based payment workflow is only quick when the phone itself is ready. That means keeping the device charged, making sure the app is easy to reach, and deciding in advance how amounts will be entered and checked. These sound like ordinary habits, but they determine whether the app saves time or merely moves the delay somewhere else.
I also recommend testing the complete interaction before using it in public. A test should include opening the app, entering a realistic amount, presenting the phone in a comfortable position, and confirming what happens after the tap. This is more useful than testing only the first screen because payment friction often appears when the seller is holding the phone, the customer is trying to position a card, and other people are waiting.
The app is free, which lowers the barrier to trying this approach. That does not mean every business should replace an existing terminal immediately. I would begin with a secondary use case: an outdoor table, a mobile appointment, a backup phone, or a short event. If the workflow feels natural there, it becomes easier to decide whether it deserves a more central role.
One non-obvious advantage is that the phone can stay with the person doing the work. A traditional reader often belongs to a location, while CPOS can follow the employee or owner. That is useful when the customer is not paying at a conventional checkout. A cleaner workflow might be to collect the amount immediately after the service, rather than writing it down and returning to a terminal later. The fewer times an amount is copied or remembered, the fewer opportunities there are for a simple mistake.
Another useful habit is to separate payment readiness from phone personalization. I would avoid relying on a device that is full of distracting notifications, nearly out of storage, or difficult to unlock quickly. CPOS may be free and compact, but it still depends on the condition of the phone around it. The app removes the need for separate payment hardware; it does not remove the need for sensible device preparation.
Everyday scenarios where the phone reader feels natural
Imagine a self-employed cleaner or repair worker finishing a visit. The customer has the amount ready, but the worker does not want to carry a terminal from appointment to appointment. With CPOS available on the working phone, payment can happen at the door instead of becoming an administrative task for later. The time saved is small for one customer, yet meaningful over a full day because it avoids follow-up messages and postponed payments.
A second scenario is a small food seller at a temporary location. The seller may have limited table space and may not want a separate reader competing with the menu, cash box, and stock. A phone can be passed or positioned at the edge of the counter for a tap. This is not automatically better than a dedicated terminal during a heavy rush, but it can be more convenient when the volume is modest and portability matters more than maximum throughput.
I can also see value for appointment-based work. A tutor, stylist, photographer, or consultant may finish in a room where there is no checkout desk. Instead of directing the customer to a payment link or asking them to remember the transaction, the seller can handle the payment in the same place as the service. That makes the end of the appointment feel complete rather than administrative.
For occasional sellers, the key benefit is avoiding over-commitment to equipment. Someone who sells at a local gathering only now and then may not want a permanent hardware setup. A free app gives that person a way to explore phone-based acceptance before investing in a more elaborate arrangement. I would still rehearse the process beforehand, because occasional use gives the seller less opportunity to build muscle memory.
The app can also help when a business has more than one practical payment position. A staff member moving around a showroom or event can potentially keep the payment step close to the customer instead of sending them to a fixed register. That reduces walking and makes the interaction more direct. The trade-off is that the business must be comfortable with the phone being used as a working tool, not just a personal device.
What friction it removes, and what it leaves behind
The clearest friction removed by CPOS is hardware dependency. There is no separate reader to find before leaving for a job, and no extra device occupying the counter. For a small operation, that simplicity matters. Fewer objects mean fewer charging routines, fewer cables, and fewer chances of arriving at a customer location without the one item needed to complete the sale.
It also reduces the distance between the seller and the customer. A fixed terminal creates a small but real movement: the customer walks to it, or the seller walks back to it. A phone reader can make the payment point travel with the conversation. In my view, this is the app’s most convincing strength. It saves time not through a flashy feature, but by removing a physical step from the transaction.
There is a useful trade-off between flexibility and specialization. A dedicated terminal is designed around payments and may feel more reassuring during a long, busy shift. A phone is more versatile, but it is also doing many other jobs. Calls, messages, low battery, screen interruptions, or a poor working environment can all affect the experience. CPOS is therefore a strong fit for mobile convenience, while a traditional reader may be better for a permanent checkout with continuous traffic.
I would also think carefully about customer confidence. Some customers may be perfectly comfortable tapping a card on a phone, while others may expect a familiar terminal. The seller can reduce uncertainty by clearly showing the amount before the customer taps and by keeping the interaction calm. The app may simplify the equipment, but good payment manners still matter: confirm the total, present the phone steadily, and wait for the transaction to finish before moving on.
Another practical insight is to treat CPOS as part of a fallback plan rather than assuming it must handle every payment situation. A business can keep its normal arrangement for the busiest location and use the phone reader when working off-site or when the main terminal is unavailable. This hybrid approach is often more realistic than demanding that one tool serve every environment. It also lets the owner judge the app by actual time saved instead of by an abstract promise of replacing hardware.
Who should use it, and who should choose something else
I would recommend CPOS to a solo operator who accepts payments in different places, a small seller who wants to reduce equipment, and a business that needs an occasional mobile option. It is particularly appealing when the payment amount is straightforward and the seller already carries a suitable phone throughout the working day. The free price makes experimentation easier, and the Everyone rating means the app is presented for a broad audience rather than a restricted age group.
I would be more cautious for a busy shop that processes a constant stream of customers. In that setting, a dedicated terminal can offer a more focused experience, especially when several employees need to use the payment setup or when the phone must remain available for other work. CPOS may still be useful as a backup, but I would not choose it automatically as the only checkout method.
It is also not the best match for a business looking for a full management platform. If the main requirement is stock tracking, staff scheduling, product catalogs, customer records, or detailed reporting, a specialized point-of-sale package will likely provide a broader foundation. CPOS’s appeal is its narrowness: it concentrates on turning the phone into a payment reader. That focus is helpful when payment is the missing piece, but limiting when the business needs an entire operating system.
Before relying on it, I would answer a few practical questions through a real trial. Can the phone be positioned comfortably for different customers? Can the seller enter amounts without slowing the queue? Does the workflow fit the business’s existing way of recording sales? Is there a backup if the phone is unavailable? These questions are more important than simply asking whether the app installs successfully. A payment tool succeeds in the space between the app screen and the real counter.
My verdict after using the phone-first approach
CPOS: Tap to Pay Card Reader solves a recurring problem in a focused way. It makes sense when the cost of carrying, charging, and locating a separate reader is greater than the benefit of having specialized hardware. For mobile sellers and small service businesses, the ability to keep payment close to the customer can remove a surprising amount of daily friction.
I like the app most as a practical companion rather than an automatic replacement for every terminal. Its free availability and compact idea make it easy to test in a low-risk situation, while its current version, 2.34.0, shows that it is an actively presented product rather than an abandoned experiment. The rating of 4.4 from over two hundred ratings also gives it a reassuring starting point for people deciding whether to try it.
My honest recommendation is to begin with one repeated scenario: the end of a mobile appointment, a small outdoor sales table, or a backup payment position. Measure the result by whether customers finish sooner, whether the seller walks less, and whether fewer payments are postponed. The real win is not owning less hardware; it is completing the payment at the moment it naturally belongs.
If that is the problem you face, CPOS is worth trying. If you need a robust register for a high-volume store or a complete business management suite, I would choose a more specialized alternative and keep this app in reserve. For the right user, though, it is a sensible business utility: simple in concept, portable in practice, and most valuable when a separate card reader feels like unnecessary baggage.
Frequently Asked Questions
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to let businesses accept contactless card and digital-wallet payments using a compatible smartphone or tablet. Instead of relying only on a traditional card terminal, the app uses the device’s NFC capability to process supported tap-to-pay transactions. It is aimed at merchants, freelancers, and small businesses that want a portable payment option.
How does Tap to Pay work with CPOS?
After installing CPOS and completing the required account or merchant setup, the seller enters the purchase amount in the app and asks the customer to hold a contactless card, phone, or smartwatch near the device. The payment is then authorized through the connected payment service. A compatible NFC-enabled device, supported operating system, internet connection, and eligible merchant account are generally required, so availability may depend on the country and provider.
Is CPOS: Tap to Pay Card Reader safe to use?
CPOS is intended to process payments through established card-payment and contactless technologies rather than storing a customer’s physical card details in the phone. Security still depends on using an updated device, protecting the merchant account, and following the provider’s verification requirements. Before accepting real payments, users should review the app’s privacy policy, transaction protections, refund procedures, and any applicable compliance responsibilities.
What devices and payment methods are supported?
Support depends on the specific CPOS release, the merchant’s location, and the payment processor connected to the application. In general, the device must include NFC and run a supported version of Android or iOS. Customers may be able to pay with contactless debit or credit cards and compatible mobile wallets. Checking the official store listing and CPOS requirements is recommended before downloading or purchasing a device.
Are there fees or limitations when using CPOS?
The application may be free to download, but accepting payments can involve processing fees, account charges, settlement conditions, or other costs determined by CPOS and its payment partners. Transaction limits, supported currencies, offline availability, refunds, and payout times can also vary by region and merchant plan. Businesses should carefully read the current pricing and service terms before replacing a conventional card terminal.


